When Americans picture the economy, they often imagine giant corporations: tech giants, Wall Street banks, national retailers. But the true engine of American economic life is far smaller and far more numerous. Small businesses, defined by the Small Business Administration as firms with fewer than 500 employees, number in the tens of millions and account for the overwhelming majority of US companies. They create jobs, drive local economies, and serve as the testing ground for new ideas. This article examines the real role small businesses play in the US economy, the challenges they face in 2026, and what their health tells us about the broader economy.
Table of Contents
- Small Business by the Numbers
- Job Creation and the Employment Engine
- Innovation and Economic Dynamism
- Local Communities and Main Street
- The Challenges Facing Small Firms in 2026
- Support Systems and Policy
- Key Takeaways
Small Business by the Numbers
The scale of American small business is staggering. According to the Small Business Administration, small firms make up more than 99 percent of all US businesses, and firms with fewer than 20 employees account for the vast majority of those. They employ roughly half of the private-sector workforce and generate a substantial share of US GDP, commonly estimated at over 40 percent. These are not marginal players; they are the economy’s foundation.
The sector is also remarkably diverse. It includes everyone from solo freelancers and family restaurants to fast-growing tech startups and mid-size manufacturers. This diversity is a strength: when one segment struggles, others often thrive, giving the small business sector a resilience that concentrated industries lack. For more on how this diversity shapes markets, see our business coverage of competitive dynamics.
New business formation has been notably strong in recent years, with Americans filing applications for new businesses at historically elevated rates. Whether this surge represents a lasting entrepreneurial wave or a temporary post-pandemic phenomenon is one of the more interesting open questions in US economics, and the answer will shape job growth for years.
Job Creation and the Employment Engine
Small businesses are disproportionate job creators. Research consistently shows that young, small firms account for an outsized share of net new jobs, even though most small businesses stay small and many fail. The pattern is driven by a minority of high-growth firms, sometimes called gazelles, that scale rapidly and hire aggressively. Today’s garage startup can be tomorrow’s major employer.
This dynamism matters for workers too. Small firms are often the first rung on the employment ladder, hiring young workers, immigrants, and people reentering the workforce. They provide training, experience, and references that launch careers. In tight labor markets, small businesses compete for talent by offering flexibility, culture, and growth opportunities that large corporations struggle to match.
But small-firm employment is also more volatile. Small businesses are more sensitive to economic downturns, credit crunches, and cost shocks, and they fail at higher rates during recessions. This cyclicality is one reason economists watch small business sentiment surveys closely: they are an early warning system for the broader labor market. Learn more in the SBA Office of Advocacy’s research on small business employment trends.
Innovation and Economic Dynamism
Small businesses punch above their weight in innovation. Studies have found that small firms produce more patents per employee than large firms, and their patents tend to be more original and more frequently cited. The reason is structural: small firms can take risks, pivot quickly, and pursue ideas that do not fit a large corporation’s existing business model.
Venture-backed startups get the headlines, but innovation happens across the small business spectrum: a manufacturer developing a new process, a restaurant pioneering a concept, a software consultancy building a novel tool. This decentralized experimentation is how market economies discover what works. Large companies often grow by acquiring successful small firms, which means small business innovation ultimately feeds corporate growth too.
Economic dynamism, the rate at which firms are born, grow, and die, has been declining in the US for decades by some measures, which worries economists who see dynamism as the wellspring of productivity growth. The recent surge in business formation may be reversing that trend. If it persists, it could be one of the more underappreciated positive developments in the American economy.
Local Communities and Main Street
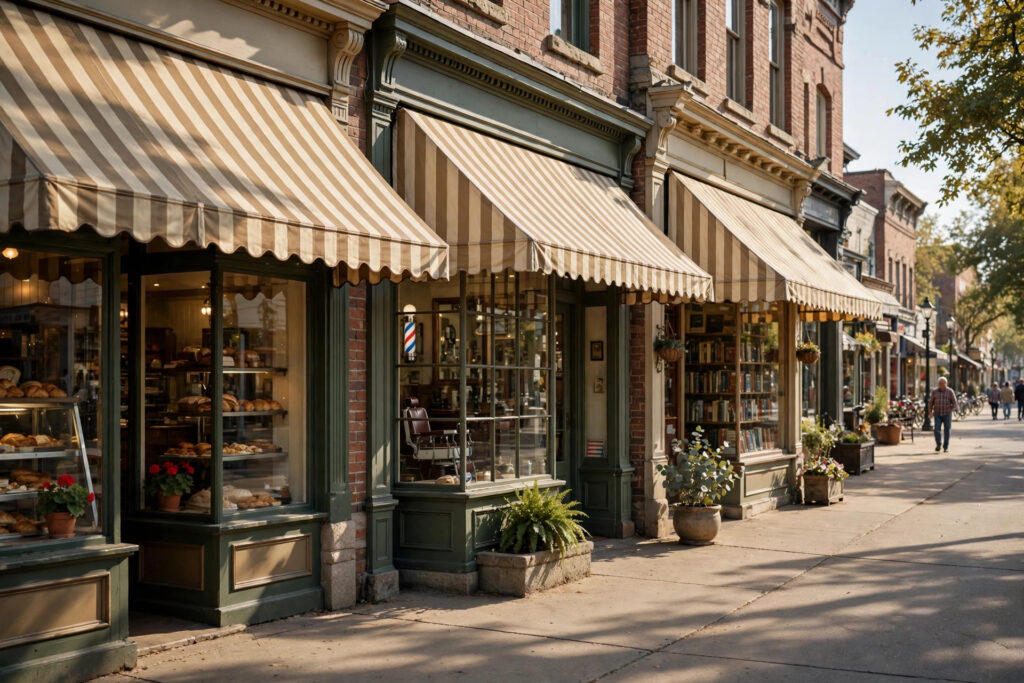
Beyond the national statistics, small businesses shape the character of American communities. Main Street shops, local restaurants, neighborhood services, and regional manufacturers keep money circulating locally: independent businesses tend to recirculate a larger share of revenue within their communities than national chains do. They sponsor youth sports, anchor downtowns, and give places their identity.
This local role became vividly clear during the pandemic, when the survival of neighborhood businesses became a community cause. The outpouring of support showed that Americans value small businesses for reasons that go beyond prices and convenience. They are social infrastructure as much as economic infrastructure.
The flip side is vulnerability. Local businesses bore the brunt of pandemic shutdowns, and many never reopened. Recovery has been uneven, with some downtowns thriving and others still struggling with empty storefronts and remote-work-driven foot traffic declines. The health of Main Street remains one of the most visible barometers of the real economy beyond Wall Street.
The Challenges Facing Small Firms in 2026
Small businesses face a daunting obstacle course. Access to capital tops the list: small firms rely heavily on bank loans and personal savings, and they feel credit tightening more acutely than large firms that can tap bond markets. According to Federal Reserve surveys of small business credit, a meaningful share of firms report difficulty obtaining the financing they need, and many do not even apply, expecting rejection.
Labor costs and availability remain pressing. Small firms compete for workers against larger employers offering richer benefits, and minimum wage increases, while good for workers, squeeze thin margins. Healthcare costs are a particular burden: small employers pay more per worker for insurance than large ones and have fewer options for managing those costs.
Regulatory compliance is another asymmetric burden. A regulation that costs a large corporation a rounding error can consume a large share of a small firm’s administrative capacity. Tax complexity, licensing requirements, and changing labor rules all hit small firms hardest. Technology helps at the margins, with affordable software automating bookkeeping and payroll, but it cannot eliminate the underlying burden.
Support Systems and Policy
A substantial support ecosystem exists for small businesses. The Small Business Administration offers loan guarantee programs, counseling through Small Business Development Centers and SCORE mentors, and disaster assistance. These programs are especially valuable for firms that cannot access conventional credit, and SBA-backed loans have helped countless businesses launch and expand.
State and local programs add another layer: tax incentives, grant programs, incubators, and procurement set-asides that direct government contracts to small firms. The federal government has longstanding goals for small business contracting, which can provide stable revenue for qualifying firms. Entrepreneurs should explore SBA programs and local resources before assuming financing is out of reach.
Policy debates continue over how best to help. Some argue for lighter regulation and lower taxes; others for stronger safety nets that make entrepreneurship less risky, such as portable health insurance decoupled from employment. What is clear is that small business health and broad economic health are inseparable: policies that help Main Street thrive tend to help the whole economy. For practical guidance on starting and running a firm, see our small business startup resources.