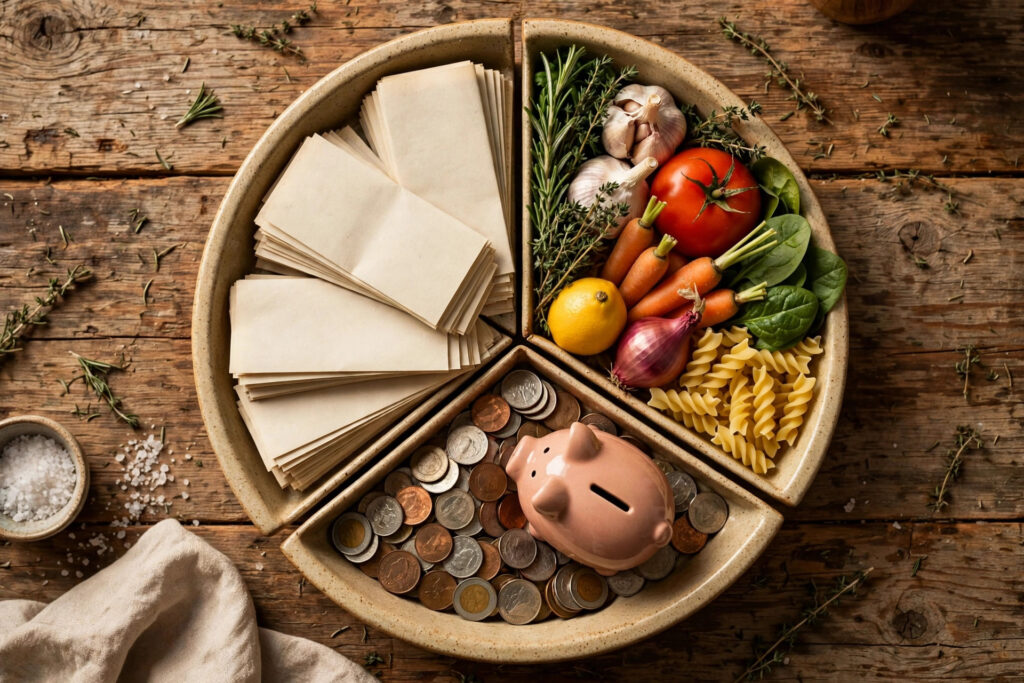
Most budgets fail for the same reason most diets fail: they are too complicated to sustain. Tracking every coffee and categorizing forty spending lines works for about three weeks, then life intervenes. The 50/30/20 budget rule endures because it does the opposite — it reduces your entire financial life to three buckets, each with a single target percentage.
Popularized by Senator Elizabeth Warren in her book on household finance, the rule has become the default starting budget for millions of Americans. This guide explains how the 50 30 20 budget rule works, what counts in each bucket, how to adapt it when your numbers do not cooperate, and when to graduate to something more detailed.
Table of Contents
- How the 50/30/20 Rule Works
- The Three Buckets: Needs, Wants, Savings
- A Worked Example
- When the Numbers Don’t Fit: Adjustments
- Making It Stick: Automation
- When to Move Beyond 50/30/20
- Key Takeaways
How the 50/30/20 Rule Works
The rule divides your after-tax income — your take-home pay, the amount that actually lands in your checking account — into three shares: 50% for needs, 30% for wants, and 20% for savings and debt repayment beyond minimums. That is the entire system. No spreadsheets with forty categories, no guilt over individual purchases, just three numbers to watch.
The genius is in what it guarantees. By fixing savings at 20% as a first-class bucket rather than “whatever is left over,” the rule ensures you pay your future self before lifestyle spending expands to fill the account. And by capping wants at 30%, it gives guilt-free permission to enjoy money — dining out, hobbies, travel — within a boundary that cannot wreck the plan.
Use after-tax income as the base, not gross salary. Taxes, pre-tax 401(k) contributions, and payroll deductions never reach your checking account, so budgeting percentages of gross pay will overstate what you can actually allocate. If your income varies month to month, base the percentages on a conservative average and treat good months as bonus savings.
The Three Buckets: Needs, Wants, Savings
Needs (50%) are the essentials required to live and work: housing (rent or mortgage), utilities, groceries, insurance premiums, transportation to work, childcare, and minimum debt payments. The test is simple: would skipping it jeopardize your housing, health, job, or legal standing? Minimum loan payments count as needs; extra debt payments belong in savings.
Wants (30%) are everything else you choose to spend: restaurants, streaming subscriptions, vacations, new clothes beyond replacements, gym memberships, gifts, and hobbies. None of this is “bad” spending — the rule explicitly protects it. The 30% cap simply forces trade-offs: a bigger vacation means fewer restaurant meals, which is exactly the kind of conscious choice budgeting is meant to produce.
Savings and debt payoff (20%) covers your emergency fund, retirement contributions beyond any employer match already deducted, extra payments toward high-interest debt, and goal-based savings like a down payment. This bucket is the engine of wealth-building — and the one most budgets starve. If you are carrying expensive credit card debt, directing most of this 20% at the balances (using the avalanche or snowball method) is usually the highest-return use.
A Worked Example
Take a household with $5,000 in monthly take-home pay:
| Bucket | Target | Monthly Amount | Examples |
|---|---|---|---|
| Needs | 50% | $2,500 | Rent $1,600, utilities $200, groceries $450, insurance $150, gas/transit $100 |
| Wants | 30% | $1,500 | Dining out $300, subscriptions $60, hobbies $200, vacation fund $400, misc $540 |
| Savings | 20% | $1,000 | Emergency fund $300, Roth IRA $400, extra debt payment $300 |
Notice what the example reveals: at this income, $2,500 for needs requires housing costs to stay reasonable. In expensive cities, the needs bucket is where the rule strains — which leads to the most important part of this guide: what to do when your reality does not match the template.
When the Numbers Don’t Fit: Adjustments
The 50/30/20 split is a starting point, not a law of physics. Common situations call for adjustments:
- High-cost cities. If rent alone consumes 45% of take-home pay, 50% for all needs is impossible. Shift to something like 60/20/20 temporarily — protecting the 20% savings rate matters more than hitting 50% on needs.
- Low incomes. When needs genuinely exceed 50%, the answer is not a different percentage but a different strategy: raising income, finding cheaper housing, or cutting fixed costs. Percentages cannot fix an absolute shortfall.
- Aggressive debt payoff. Households attacking high-interest debt often run 50/10/40 for a season — slashing wants to supercharge the savings bucket until the debt is gone.
- High earners. At higher incomes, needs may naturally fall well below 50%. Resist lifestyle inflation by holding wants near 30% and letting savings absorb the surplus — 30% or 40% savings rates build wealth remarkably fast.
The non-negotiable principle: savings is the last bucket to cut, not the first. When budgets get tight, people instinctively raid savings to protect lifestyle spending; the rule’s structure exists precisely to reverse that instinct. For perspective on how household budgets interact with national trends, see our analysis of consumer spending in the US economy.
Making It Stick: Automation
A budget you have to think about every day is a budget you will abandon. The 50/30/20 rule works best when the 20% never touches your checking account:
- Pay yourself first. Set automatic transfers on payday: 20% to savings and investment accounts before you spend anything. Our guide to automating your savings walks through the setup.
- Separate the buckets. Keep wants spending on one account or card with a monthly cap, so overspending is visible immediately.
- Review monthly, not daily. A ten-minute monthly check — are the three percentages roughly on target? — is enough. Daily tracking burns people out.
- Adjust quarterly. Rents rise, incomes change, goals evolve. Recalibrate the dollar amounts every few months.
Couples should run the rule on combined take-home pay with shared visibility — money disagreements usually trace back to unspoken assumptions about which bucket a purchase belongs in. Agreeing on the three numbers upfront prevents most fights.
When to Move Beyond 50/30/20
The rule’s simplicity is also its ceiling. Consider graduating when: you want to optimize aggressively (zero-based budgeting assigns every dollar a job), you are pursuing financial independence (savings rates of 40–50%+ require finer control), or your finances involve business income, rentals, or complex taxes that three buckets cannot capture.
But graduation should be a step up, not a collapse back to nothing. Many sophisticated budgeters keep 50/30/20 as a dashboard metric — a quick monthly health check — even after adopting detailed systems underneath. If your savings rate is consistently at or above 20% and your needs are under control, the rule has done its job, whatever system you use next. The Federal Deposit Insurance Corporation’s money-management resources, linked via usa.gov, offer free worksheets for those ready to go deeper.