Certificates of deposit pay some of the best guaranteed returns available to savers — but they come with a catch: your money is locked up for the term, and breaking the lock early triggers penalties. That trade-off pushes many people into one of two bad choices: keeping everything in a low-yield savings account for flexibility, or locking everything into a single long CD for yield.
CD laddering splits the difference elegantly. By spreading money across CDs with staggered maturities, you earn long-term rates while keeping a portion of your cash freeing up on a regular schedule. This guide explains how CD laddering works, how to build a ladder step by step, when it makes sense, and the mistakes that undermine it.
Table of Contents
- What Is a Certificate of Deposit?
- How CD Laddering Works
- Building Your Ladder Step by Step
- The Benefits of Laddering
- When Laddering Doesn’t Make Sense
- Common CD Laddering Mistakes
- Key Takeaways
What Is a Certificate of Deposit?
A certificate of deposit is a bank product where you agree to leave money deposited for a fixed term — anywhere from a few months to five years or more — in exchange for a guaranteed interest rate, the CD’s APY. Because the bank can count on holding your money, CDs typically pay more than liquid savings accounts, with longer terms generally paying higher rates.
CDs are among the safest places to keep money: deposits at banks are FDIC-insured up to the legal limits, and the rate is locked regardless of what markets do. The price of that safety and yield is liquidity — withdrawing before maturity usually costs an early-withdrawal penalty, often several months’ worth of interest.
That penalty creates the central tension of CD investing. Lock in a great 5-year rate and you earn well — unless you need the money in year two. Keep everything liquid and you earn little. Laddering resolves the tension structurally rather than by guessing right about the future.
How CD Laddering Works
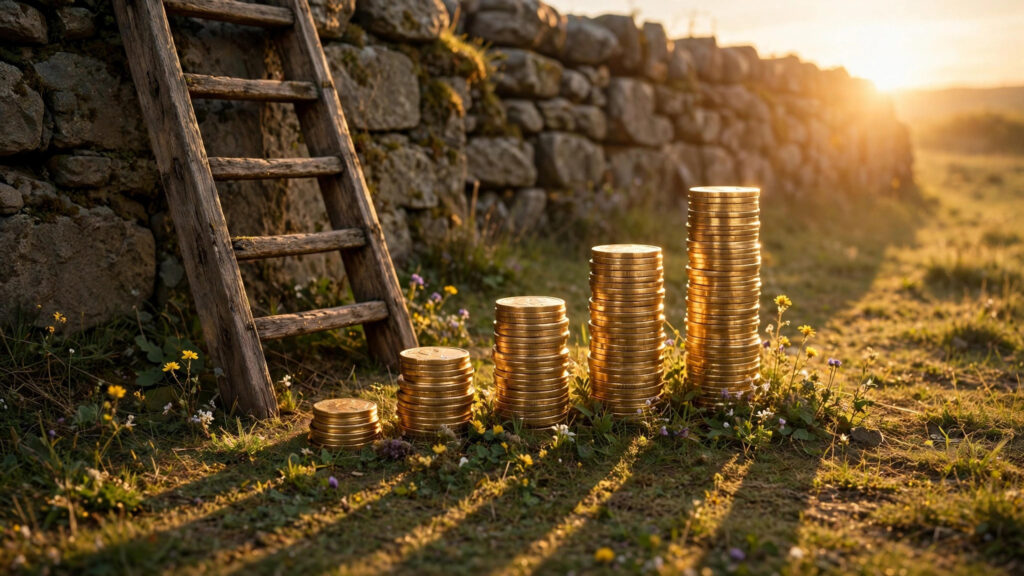
A CD ladder divides your savings into equal portions and staggers them across maturities. The classic example: with $25,000, you put $5,000 each into 1-year, 2-year, 3-year, 4-year, and 5-year CDs. After one year, the 1-year CD matures — and you roll it into a new 5-year CD at the prevailing rate. Each year after that, another rung matures and gets reinvested at the long-term rate.
Once the ladder is running, you hold five CDs earning 5-year rates, yet $5,000 becomes available every twelve months. You get the yield of long-term commitments with the accessibility of a one-year horizon. If rates rise, each maturing rung captures the higher rate; if rates fall, most of your money is still locked at the older, higher rates — the ladder smooths interest-rate risk in both directions.
The structure is flexible. A shorter ladder (say, 6-month rungs over two years) suits money you might need sooner; a longer ladder maximizes yield for money you will not touch. The principle is identical at any scale: stagger maturities, reinvest maturing rungs at the long end, and let the system run. For money with a known deadline — a house down payment in three years — a high-yield savings account or a single CD matched to the date may be simpler; laddering shines for cash with an uncertain timeline.
Building Your Ladder Step by Step
- Decide the total amount. Use money you will not need imminently — laddering complements, not replaces, your liquid emergency fund. Many savers ladder funds earmarked for medium-term goals.
- Choose the number of rungs. Five rungs is the classic, but three to ten all work. More rungs mean more frequent access and finer rate-averaging; fewer rungs mean less management.
- Pick the rung spacing. Annual rungs over five years are standard. For a shorter horizon, use 3- or 6-month spacing over one to two years.
- Shop rates aggressively. Online banks and credit unions routinely beat branch banks by a wide margin. Compare APY, early-withdrawal penalties, and minimum deposits — and confirm FDIC or NCUA insurance.
- Open all rungs at once (or build gradually by opening the shortest rung first and adding longer ones as savings accumulate).
- Reinvest each maturing rung into a new longest-term CD — this is the step that keeps the ladder climbing. Set calendar reminders for maturity dates.
Brokered CDs — bought through a brokerage rather than directly from a bank — are an alternative worth knowing: they often offer competitive rates and can be sold on a secondary market, though selling early can mean accepting a market price below face value. Direct bank CDs with clear penalty terms are simpler for most ladder builders.
The Benefits of Laddering
- Higher yields than liquid savings. Long-term CD rates typically exceed savings account APYs, and the ladder keeps you earning them continuously.
- Regular liquidity. A rung matures on schedule — no penalties, no dilemmas — giving you periodic access to a slice of the funds.
- Interest-rate smoothing. Rising rates get captured as rungs mature; falling rates leave most of the ladder locked at higher yields. You never have to predict the Fed.
- Zero market risk. Unlike bonds or bond funds, CDs cannot lose principal to rate movements (held to maturity), and deposits are federally insured.
- Behavioral guardrails. The mild friction of early-withdrawal penalties discourages impulse spending while keeping true emergencies accessible at a known cost.
For retirees and conservative savers, a ladder can form the safe core of a portfolio — predictable income with staggered access — while risk assets handle growth elsewhere. It pairs naturally with an understanding of how interest rates move, since the ladder is essentially a mechanical way to harvest the yield curve without forecasting it.
When Laddering Doesn’t Make Sense
Laddering is not universal. Skip it — or keep the ladder small — when:
- You need the money soon. Cash needed within a year belongs in a high-yield savings account, not a ladder.
- Rates are deeply inverted or tiny. If long-term CDs pay barely more than liquid savings, the complexity earns you almost nothing — wait for a wider spread.
- You can earn far more elsewhere. Money earmarked for retirement decades away belongs in diversified investments, where expected returns dwarf any CD.
- Simplicity matters more. A single high-yield savings account you actually maintain beats an elaborate ladder you abandon. Personal finance rewards systems you will sustain.
Also weigh taxes: CD interest is taxable as ordinary income in the year it accrues (or is credited), so hold CDs in taxable accounts only with eyes open — in high brackets, the after-tax edge over savings accounts narrows. The IRS explains interest income reporting at irs.gov.
Common CD Laddering Mistakes
The most common error is laddering the emergency fund. Emergency money must be instantly accessible without penalty — a CD ladder’s scheduled access is not the same as on-demand access, and breaking CDs in a crisis forfeits the yield you built the ladder to capture. Keep the emergency reserve liquid; ladder only surplus savings.
Other mistakes: chasing the absolute highest rate at an unfamiliar institution without verifying insurance; forgetting to reinvest maturing rungs (many banks auto-renew into the same term, which is fine, but some default to low-rate rollovers); building rungs so small that the yield difference is trivial relative to the hassle; and locking money into long CDs right before a known large expense. A few minutes of planning per rung avoids all of these. The FDIC’s consumer resources, linked via usa.gov, explain deposit insurance limits that matter when spreading large sums across institutions.